
Revision summary
Parliamentary committees are standing, financial, administrative and ad hoc. DRSCs since 1993 examine grants, bills and ministry policy with both Houses. PAC, Estimates Committee and COPU are the three financial committees. PAC works on CAG reports and is conventionally chaired by the Opposition. They institutionalise continuous financial scrutiny, not a veto on Supply. Weak follow-up of recommendations is the main limit on that institutionalisation.
Model answer
Copper italics in this answer — like this — are the key facts. Each one is unpacked in the Facts & figures rail.
Introduction
Parliament cannot examine every clause and every rupee on the floor of the two Houses. Committees are how it institutionalises scrutiny: standing, financial, and ad hoc bodies that work across the year in a less partisan room.
Body
Structure of the committee system
- Committees are of three broad kinds: standing committees that are reconstituted regularly, ad hoc committees (select, joint, and inquiry) for a bill or a scandal, and administrative committees of each House (Rules, Privileges, Business Advisory).
- Departmentally Related Standing Committees, created in 1993 and later expanded, cover Union ministries; they examine Demands for Grants, bills, and long-term policy, and they have members from both Lok Sabha and Rajya Sabha.
- Each House also has subject committees of its own, such as the Committee on Petitions and the Committee on Subordinate Legislation, which watch rules made under statutes.
- Joint Parliamentary Committees are appointed by motion of both Houses when a bill or a controversy needs a single high-visibility probe.
- The Presiding Officers constitute most committees; party strength in the House is reflected in membership, which is why the system is parliamentary, not a separate fourth branch.
The three financial committees
- The Public Accounts Committee examines appropriation and finance accounts and the reports of the Comptroller and Auditor General of India; by convention its Chair is from the Opposition, and Rajya Sabha members sit with a Lok Sabha majority.
- The Estimates Committee, drawn from the Lok Sabha, examines whether money is well laid out within the policy that Parliament has voted, and it suggests economies and alternative forms of organisation.
- The Committee on Public Undertakings examines the reports and accounts of public sector undertakings and CAG reports on those undertakings; it is not a substitute for a company board.
- Together they follow the rupee after the Budget is passed, which the floor cannot do line by line.
Institutionalisation of Parliament
- Financial committees made scrutiny a routine of the calendar, not a one-day Budget speech: CAG reports go to PAC; undertakings go to COPU; estimates go to a Lok Sabha committee.
- Bipartisan membership and in-camera evidence create an institutional memory of ministries that dissolves less quickly than a Lok Sabha majority.
- They cannot withhold Supply; the House still votes the Demands. Institutionalisation is therefore examination and publicity, not a second budget veto.
- Limits are real: delayed CAG reports, poor ministerial implementation of PAC recommendations, party whips on sensitive findings, and the absence of a dedicated parliamentary budget office.
- DRSCs after 1993 extended the same method from money to ministries; financial committees remain the oldest core of that method, inherited from colonial Public Accounts practice and rewritten for a republican CAG under Articles 148 to 151.
How far
- They have institutionalised Parliament as a continuous audit forum, especially PAC with the CAG.
- They have not institutionalised Parliament as a co-equal fiscal policymaker; that still sits with the executive’s Budget.
Flow diagram
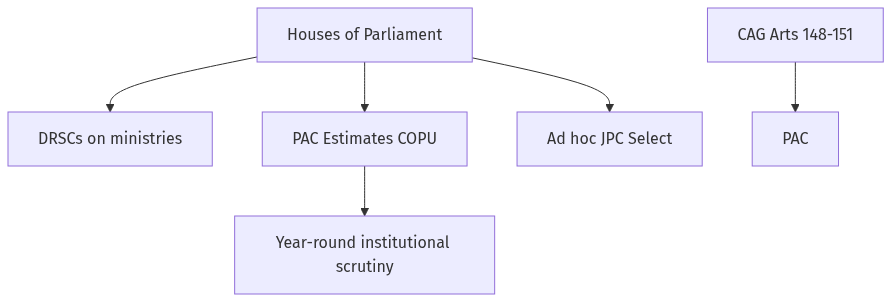
Conclusion
The committee system is standing, financial, and ad hoc, with DRSCs wrapping ministries and three financial committees wrapping the rupee. PAC, Estimates and COPU have institutionalised year-round financial scrutiny; they have not taken the Budget away from the executive, and implementation of their reports is still the unfinished test.
Quick related
Students also ask
-
Discuss the procedures to decide the disputes arising out of the election of a Member of the Parliament or State Legislature under The Representation of the People Act, 1951. What are the grounds on which the election of any returned candidate may be declared void? What remedy is available to the aggrieved party against the decision ? Refer to the case laws.
Next question on this syllabus topic (2022 · Q11). View answer →
-
Can PAC cut a ministry’s budget?
No. It reports after expenditure. The House votes Supply. PAC’s power is exposure and recommendation, aided by the CAG.
-
Is a DRSC the same as a financial committee?
No. DRSCs cover a ministry’s policy and grants. PAC, Estimates and COPU are the specialised financial trio.
Same topic · past papers
UPSC has asked this before
These previous-year questions sit on the same topic. Open one to practise the earlier ask.
-
2025 · Q14 · GS II · 15 marks
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India? -
2018 · Q3 · GS II · 10 marks
Under what circumstances can the Financial Emergency be proclaimed by the President of India? What consequences follow when such a declaration remains in force?
More from this topic
Q3 · UPSC Mains 2026 · GS II · 10 marks · Solution
Examine whether the constitutional office of the Lok Sabha Speaker has become vulnerable to partisan politics under the current anti-defection regime. What institutional changes are required to ensure the neutrality of the Lok Sabha Speaker in managing a polarised House?
Parliament and State Legislatures
• The Lok Sabha Speaker faces a conflict of interest because they remain in a political party while deciding disqualification cases under the Tenth Schedule. • Key vulnerabilities include dual political allegiance, weaponization of the anti-defection whip for government stability, and tactical delays in rulings. • The Supreme Court (*Keisham Meghachandra Singh*, 2020) criticized these delays and suggested moving to an independent tribunal. • Reform idea 1: Adopt the British convention where the Speaker cuts all party ties and runs unopposed in elections. • Reform idea 2: Shift defection adjudication entirely away from the Speaker to an outside body like the Election Commission. • Reform idea 3: Enforce strict statutory time limits to prevent politicians from stalling defection cases during crises.
Q2 · UPSC Mains 2026 · GS II · 10 marks · Solution
"Women as a class neither belong to a minority group nor are they regarded as forming a backward class." In the light of this statement, discuss the evolution of women's reservation from local bodies to Parliament.
Parliament and State Legislatures
• Women form a cross-cutting demographic, not a traditional minority or caste-based backward class.
Q12 · UPSC Mains 2025 · GS II · 15 marks · Solution
Indian Constitution has conferred the amending power on the ordinary legislative institutions with a few procedural hurdles. In view of this statement, examine the procedural and substantive limitations on the amending power of the Parliament to change the Constitution.
Parliament and State Legislatures
Article 368 uses Parliament’s Houses, not a standing constituent assembly, with special majority and no joint sitting. Federal provisions need ratification by at least half the States. Ordinary Acts cannot amend the Constitution. Kesavananda, Minerva Mills, Indira Gandhi and I.R. Coelho set substantive basic-structure limits, including judicial review and rights-DPSPs balance. NJAC 2015 shows the doctrine applying to institutional design, not only to rights texts.