
Revision summary
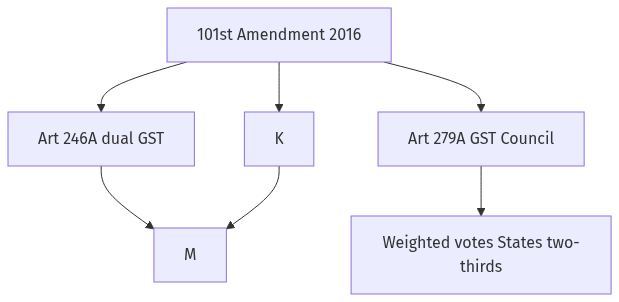
The 101st Constitutional Amendment, 2016, introduced GST through Articles 246A, 269A and 279A. It subsumed many Union and State indirect taxes into CGST, SGST and IGST. The GST Council gives States two-thirds vote weight and the Union one-third, with a three-fourths decision rule. Five-year compensation was the federal bargain; dual GST kept States as taxing governments. Mohit Minerals held Council recommendations not strictly binding law. Accommodation is real in design and strained in revenue politics after compensation.
Model answer
Copper italics in this answer — like this — are the key facts. Each one is unpacked in the Facts & figures rail.
Introduction
The Constitution (One Hundred and First Amendment) Act, 2016, introduced a national Goods and Services Tax by rewriting the Union and State tax lists. Its significance is a common market; its federal test is whether States remain partners in rate-setting and revenue, not only collecting agents.
Body
Significance of the 101st Amendment
- It inserted Article 246A, which gives Parliament and State legislatures concurrent power to tax goods and services (with exclusive Union power over inter-State GST).
- It inserted Article 269A for inter-State GST apportionment and Article 279A for the Goods and Services Tax Council.
- It subsumed a stack of Union and State taxes — including Central Excise on goods, Service Tax, VAT, octroi and entry tax, and several cesses — into CGST, SGST and IGST.
- It enabled the Goods and Services Tax (Compensation to States) Act, 2017, which promised States compensation for five years for revenue shortfall below a 14 per cent annual path, funded by a compensation cess.
- Economically it cut cascading tax-on-tax, unified the domestic market, and created a digital matching system through the Goods and Services Tax Network.
Accommodative federalism in the design
- The GST Council is a constitutional body, not a mere advisory board; States sit with the Union, and the Union’s vote weight is one-third while States together hold two-thirds.
- A decision requires a three-fourths majority of weighted votes of members present and voting, so the Union cannot, on paper, steam-roll a united State bloc.
- Dual GST (Centre and State on the same base) preserved the State as a taxing sovereign, unlike a purely central VAT.
- Compensation for five years was the political bargain that brought reluctant manufacturing and consuming States into the 2016 settlement.
- Petroleum, alcohol for human consumption, and stamp duty on land remaining outside GST show that States kept some independent tax handles.
Limits of that accommodation
- In practice the Union’s one-third vote plus a few aligned States can pass a rate decision; “consensus” has often been political, not a veto for every State.
- In Union of India v. Mohit Minerals (2022) the Supreme Court held that Council recommendations are not binding in the sense of a law; Parliament and State legislatures still enact, which both protects legislative federalism and creates uncertainty.
- Compensation ended in June 2022 as originally timed; extension of cess to repay borrowed compensation, and disputes over IGST settlement, showed that the bargain was time-bound.
- Rate changes, cess on luxury items, and delayed GST Appellate Tribunals have left small dealers and some States unhappy even while the common market holds.
Extent
- The 101st Amendment is accommodative in structure: concurrent tax power, a Council, dual GST, and a compensation deal.
- It is less accommodative in operation when revenue stress meets a strong Union agenda. It is cooperative federalism with an imbalance, not a return to isolated State VATs.
Flow diagram
Conclusion
The 101st Amendment is significant because it created a constitutional common market and a GST Council. It reflects accommodative federalism in dual GST, vote weights, and compensation, and it falls short where the Union’s agenda and the end of guaranteed compensation squeeze State fiscal space.
Quick related
Students also ask
-
The jurisdiction of the Central Bureau of Investigation(CBI) regarding lodging an FIR and conducting probe within a particular state is being questioned by various States. However, the power of States to withhold consent to the CBI is not absolute. Explain with special reference to the federal character of India.
Next question on this syllabus topic (2021 · Q11). View answer →
-
Did States lose the power to tax after GST?
They lost many old taxes such as VAT on most goods. They gained SGST on a common base and a seat on the Council. Some items such as alcohol remain with States.
-
Is the GST Council a third legislature?
No. Mohit Minerals treated it as a recommendatory constitutional forum. Laws are still made by Parliament and State legislatures.
Same topic · past papers
UPSC has asked this before
These previous-year questions sit on the same topic. Open one to practise the earlier ask.
More from this topic
Q13 · UPSC Mains 2026 · GS II · 15 marks · Solution
How far has the Indian federal framework been successful in accommodating regional and cultural diversities? Highlight the role of asymmetric federalism and suggest measures to make dispute resolution mechanisms more effective.
Federal Structure and Devolution
• Linguistic reorganisation from 1953 to 1966 gave regional identities an institutional home inside the Union • The Eighth Schedule now lists twenty-two languages and classical language status has widened • The Fifth and Sixth Schedules and Articles 371 to 371J create tailored autonomy for tribal and border regions • Friction continues in language policy, the 2019 changes in Jammu and Kashmir, Manipur and fiscal and delimitation concerns • Asymmetric federalism converts demands into negotiated settlements but needs funds and trust • Dispute machinery includes the Inter-State Council, Zonal Councils, GST Council, tribunals and Article 131 suits • The Inter-State Council meets rarely, and river tribunals are slow • Reforms include a permanent Council secretariat, a single water tribunal, technical panels and mediation
Q11 · UPSC Mains 2026 · GS II · 15 marks · Solution
Discuss the position of the Governor in the federal polity of India. What is the nature of his power while giving assent to a bill passed by the State Legislature? Is he bound by the aid and advice of his Council of Ministers in all his functions?
Federal Structure and Devolution
• The Governor is the nominal executive head of the State under Articles 153 to 159, appointed by the President and holding office during his pleasure • He links the Union and the State, which gives the office a federal role and a political edge • Article 200 lets him assent, withhold, return a non-money bill, or reserve it for the President • Assent is a constitutional duty guided by legality, not a personal veto, and bills cannot be left pending indefinitely • Recent Supreme Court rulings in the Tamil Nadu dispute and the later Presidential Reference tackled timelines and pocket veto • Article 163 makes aid and advice the rule, with discretion only in narrow express or situational areas • Shamsher Singh and Nabam Rebia limit discretion and make it reviewable • Sarkaria and Punchhi reforms on appointment, tenure and timelines remain relevant
Q14 · UPSC Mains 2025 · GS II · 15 marks · Solution
Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?
Federal Structure and Devolution
Finance Commissions devolve taxes; Planning Commission Plan grants created a discretionary second channel. Sarkaria and Punchhi criticised that discretion. NITI Aayog ended Plan cheques; 14th FC raised the States’ share of the divisible pool to 42%. GST shares tax but limits State rate power; cesses outside the pool and CSS keep Union leverage. Article 293 borrowing conditions remain a hard federal tool.