
Revision summary
The 101st Amendment inserted Articles 246A, 269A and 279A for GST, IGST and the GST Council. Dual GST with input-tax credit is the tool against cascading. A common market needs destination-based IGST and a single compliance spine. Petroleum, alcohol, multiple slabs and inverted duty keep some cascade and some borders. The Amendment is legally sufficient; working efficacy is still partial.
Model answer
Copper italics in this answer — like this — are the key facts. Each one is unpacked in the Facts & figures rail.
Introduction
The Constitution (One Hundred and First Amendment) Act, 2016 inserted a goods and services tax into the federal bargain so that a chain of Union and State levies could become one destination-based tax. Cascading means tax on tax when credit is denied. A common national market means a trader can move goods and services across State borders without a fresh fiscal wall at each check-post. The Amendment is the legal engine; efficacy is whether credit, rates and the GST Council actually deliver that promise.
Body
Salient features of the 101st Amendment
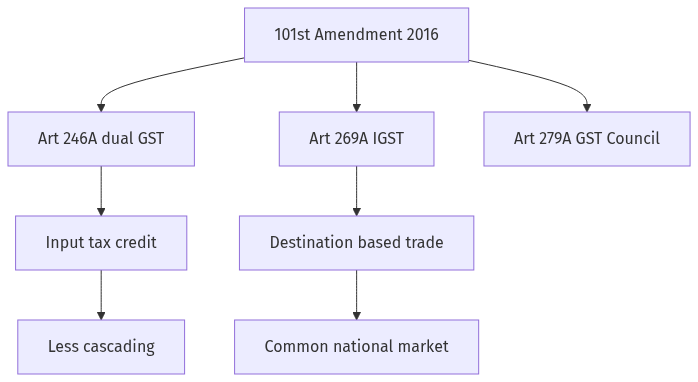
- It inserted Article 246A, which gives Parliament and the State legislatures concurrent power to make laws on GST, while exclusive power over inter-State GST remains with Parliament.
- Article 269A provides for levy and collection of integrated GST on inter-State supplies, with apportionment between the Union and the States on GST Council recommendations.
- Article 279A constitutes the GST Council, chaired by the Union Finance Minister, with State finance ministers as members, to recommend rates, exemptions, model laws, and the principles of supply and place of supply.
- Council decisions need a three-fourths weighted majority of members present and voting, with one-third weight for the Union and two-thirds for the States taken together, which is cooperative federalism written as a voting rule.
- The Seventh Schedule was recast: Union and State entries on excise and sales tax were narrowed so that GST could occupy the field, while alcoholic liquor for human consumption stayed with the States, and specified petroleum products, electricity and a few other items were kept outside GST until the Council recommends otherwise.
- Article 366 was amended to define GST, and the older service-tax Article 268A was omitted. Compensation to States for revenue loss for a transition period was written into the Amendment’s statement of objects and later into the GST (Compensation to States) Act, 2017.
- Dual GST is the working form: Central GST and State GST on intra-State supplies, and IGST on inter-State supplies and imports, with input-tax credit intended to flow along the chain.
Removing the cascading effect
- Cascading fell where the credit chain is complete: a manufacturer or trader can set off GST paid on inputs against GST on output, which the old Central Sales Tax and many cascading State levies did not allow across the full chain.
- Efficacy is incomplete while petrol, diesel, natural gas, aviation turbine fuel, crude oil and electricity remain outside GST, because freight and factory costs still carry a buried tax that cannot be credited.
- Multiple rate slabs, cess on luxury and sin goods, and inverted duty structures (higher tax on inputs than on output) recreate pockets of unusable credit, which is cascading by another name.
- E-way bills, invoice matching and anti-profiteering were meant to police the credit trail; they reduce evasion but also raise compliance cost for small firms, so some cascading is replaced by a paperwork tax.
A common national market
- Octroi-style check-posts and the Central Sales Tax origin bias were the old map of a fragmented market. Destination-based GST plus IGST is designed as one market with a credit trail across State lines.
- The GST Network, a common registration and return spine, and the Council’s power to harmonise rates, are the institutional market, not only the tax name.
- The market is still not fully common: State compensation politics, rate wars through exemptions, and delayed refunds on exports and inverted duty break the promise of frictionless trade.
- Alcohol and petroleum staying out means two large consumption goods still face State-wise fiscal borders.
Is it efficacious enough?
- As a constitutional design, yes: 246A, 269A and 279A are enough to kill the old cascade and to build a national market if credit is universal and rates are few.
- As a working tax in 2017 and after, only partly: the Amendment opened the door; exclusions, slabs and federal bargaining keep some cascade and some borders alive.
- Efficacy will rise when petroleum and electricity enter GST, refunds are timely, and the Council treats one-rate simplicity as a market good, not only as a revenue good.
Flow diagram
Conclusion
The 101st Amendment’s salient features are concurrent GST power, IGST, the GST Council, a recast Seventh Schedule, and a dual destination-based tax with credit. That design is efficacious enough in law to remove cascading and to found a common national market. It is not yet efficacious enough in practice while petroleum, alcohol, inverted duties and multi-slab politics keep tax-on-tax and State-wise friction alive.
Quick related
Students also ask
-
To what extent is Article 370 of the Indian Constitution, bearing marginal note "temporary provision with respect to the State of Jammu and Kashmir", temporary? Discuss the future prospects of this provision in the context of Indian polity.
Next question on this syllabus topic (2016 · Q2). View answer →
-
Did the 101st Amendment abolish all State tax power on goods?
No. Alcohol for human consumption remains a State subject, and specified petroleum products stay outside GST until the Council recommends inclusion.
-
Why does cascading still appear after GST?
Credit cannot run through excluded fuels and electricity, and inverted rates plus delayed refunds trap tax in the chain. That is a design-and-administration gap, not a missing Article.
Same topic · past papers
UPSC has asked this before
These previous-year questions sit on the same topic. Open one to practise the earlier ask.
More from this topic
Q17 · UPSC Mains 2026 · GS II · 15 marks · Solution
Can the constitutional mandate of rights-based welfare be effectively realised in the context of non-integrated governance and minimal public investment? Examine.
Indian Constitution
Rights-based welfare has a strong constitutional and statutory base, but silos across ministries and levels, low social-sector spending and rationed funds weaken delivery. DBT, mission-mode schemes, ration portability and district convergence help only when funding and local capacity grow with them.
Q1 · UPSC Mains 2026 · GS II · 10 marks · Solution
Right to privacy relating to self-identity is very dear to every human being and well protected under Article 21 of the Constitution. In this context, examine the effect of the amendment in 2026 to the Transgender Persons (Protection of Rights) Act, 2019.
Indian Constitution
• Gender identity is part of dignity, autonomy and privacy under Article 21, as held in NALSA and Puttaswamy. • The 2019 Act already weakened self-identification through the District Magistrate certificate route. • An amendment that adds medical or board scrutiny turns a right into a permission. • Collecting medical history creates data risks and fails the proportionality test when gentler options exist. • Intersex variation and gender identity are different and should not sit under one test. • Remedies are weak without strong penalties, reservation and working institutions. • A fair design keeps self-declaration, confidential records, time limits and community participation.
Q3 · UPSC Mains 2025 · GS II · 10 marks · Solution
Compare and contrast the President's power to pardon in India and in the USA. Are there any limits to it in both the countries? What are 'preemptive pardons'?
Indian Constitution
Article 72 (and 161) are exercised on aid and advice; Maru Ram, Kehar Singh, Epuru Sudhakar and Shatrughan Chauhan frame Indian limits and delay. The US Article II pardon is personal, federal-only, and barred in impeachment. Judicial review is stronger in India; political cost is the main US brake. A preemptive pardon forgives before conviction, as in Ford–Nixon. India has no working doctrine of preemptive pardon for the untried.