
Revision summary
Tariffs and non-tariff barriers in big markets hit Indian merchandise exports. Oil, fertiliser, and chip controls raise costs and the current-account bill. Capital flight in a tense world can weaken the rupee. Home logistics and standards add obstacles even before a foreign tariff. FTAs, PLI, and mixed import sources are cushions, not a full shield.
Model answer
Introduction
India trades in a world of tariffs, sanctions, shipping shocks, and friend-shoring. Global tension does not stay offshore. It enters the factory as cost, the port as delay, and the budget as subsidy or duty.
Body
Channels of impact
- Extra tariffs and non-tariff barriers in large markets cut merchandise exports in labour-intensive lines such as garments, gems, and some engineering goods.
- Sanctions, payment blocks, and shipping risk raise the price of oil, fertiliser, and other bulk imports, which feeds wholesale inflation and the current-account bill.
- Export controls on chips, machines, and dual-use technology slow some manufacturing upgrades even when India is not the target of the dispute.
- Capital flows become jumpy in a risk-off world, which can pressure the rupee and make imported capital goods dearer.
Obstacles at the border
- Logistics cost, standards, rules of origin, and slow refunds are home-grown export obstacles that pile on top of foreign tariffs.
- Diversion of trade — China plus one, or new regional pacts — can help some sectors and hurt others that lose a cheap intermediate.
Indian response in outline
- FTAs, Production Linked Incentive, and market diversification try to keep orders when one partner turns protectionist.
- Strategic reserves and mixed import sources limit oil and fertiliser shocks.
- Domestic demand remains a buffer, but it cannot fully replace lost export jobs.
- The impact is therefore mixed: some import substitution and some export pain, with inflation risk when energy is blocked.
Flow diagram
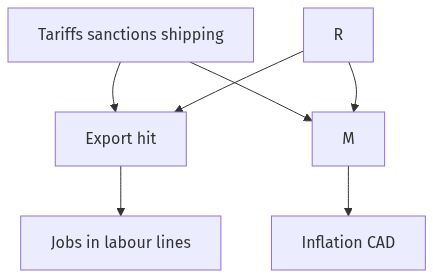
Conclusion
Global tensions and trade obstacles raise India’s import bill, rattle exports, and complicate technology access. Diversification, FTAs, and domestic demand cushion the blow; they do not cancel a tariff or a shipping shock.
Quick related
Students also ask
-
"Investment in health and education forms the foundation of economic development." Explain the views of the Government of India in this context.
Next question in the 2025 paper (Q14). View answer →
-
Do tensions only hurt India?
They also create China-plus-one orders. The net effect depends on the sector.
-
Can domestic demand replace exports?
It cushions GDP. It does not fully replace factory jobs that were tied to foreign buyers.
Same topic · past papers
UPPSC has asked this before
These previous-year questions sit on the same topic. Open one to practise the earlier ask.
More from this paper
Q1 · UPSC Mains 2025 · UPGS3 · 8 marks · Solution
Identify the critical challenges faced by the handicraft industries in India and discuss their challenges.
Food processing
Handicrafts are large in jobs but weak in organisation. Costly inputs, middlemen, and machine-made copies cut the artisan’s price. Credit, GST paperwork, and export compliance are hard for household units. GI tags and e-commerce help some clusters, not the whole sector. The challenge is to move skill, credit, and direct sale to the maker.
Q2 · UPSC Mains 2025 · UPGS3 · 8 marks · Solution
"Construction of new airports will facilitate industrialization and development in India." Examine.
Infrastructure
Airports can shorten time to markets and support logistics jobs. UDAN tries to spread air access beyond metros. Land, wetlands, and noise are real costs of greenfield sites. Thin traffic means some airports need heavy subsidy and still do not pull factories. Industrialisation needs hinterland demand, not only a terminal.
Q3 · UPSC Mains 2025 · UPGS3 · 8 marks · Solution
Discuss the concept of unemployment in India as developed by National Sample Survey Office (NSSO).
Poverty, unemployment and inclusive growth
India measures unemployment on more than one reference period because work is often casual. Usual status (ps and ps+ss) uses the last year and usually gives the lowest rate. Current weekly status uses the last seven days. Current daily status counts person-days and captures underemployment. PLFS is the present NSO survey that carries these NSSO concepts.