
Revision summary
PMFBY is the chief crop insurance in U.P., with weather-based cover beside it. Farmer premium is capped; Union and state share the rest. A timely claim is real risk transfer and supports credit. Area yield can miss one wrecked plot; delays teach opt-out. Awareness and horticulture fit remain the state gaps.
Model answer
Introduction
Farm risk in Uttar Pradesh is monsoon, hail, flood, and price. Crop insurance, chiefly Pradhan Mantri Fasal Bima Yojana, is the public tool that turns a failed field into a cheque. Impact is real where the cheque arrives; it is theatre where assessment is late or the farmer never enrolled.
Body
The schemes
- PMFBY is the main yield-based cover, with a capped farmer premium and the rest shared by Union and state.
- Weather-Based Crop Insurance covers specified weather triggers where yield measurement is hard.
- State machinery notifies crops and seasons, runs enrolment through banks and CSCs, and must pay its subsidy share on time or the insurer stalls.
- Optional enrolment after earlier phases changed the coverage map; many loanee farmers remain the captive base.
Impact on risk management
- A working PMFBY cheque after drought or flood stops distress sale of animals and some debt spirals, which is genuine risk transfer.
- Banks lend more calmly when the kharif crop is insured, so insurance is also a credit tool.
- Area-based yield assessment can miss a single wrecked plot, which is why farmers call it average justice.
- Delayed claims teach the farmer that insurance is a lottery, which raises opt-out and weakens the pool.
Gaps in U.P.
- Awareness in eastern and Bundelkhand small holdings is still thin; many know the bank deduction, not the claim path.
- Crop-cutting experiments and satellite use have improved speed in places, but disputes at the village remain.
- Horticulture and mixed holdings are harder to fit into a notified grain-centric list.
- Risk management is therefore partial: better than no cover, weaker than a household that still needs MNREGA and a grain heap after a failed season.
Flow diagram
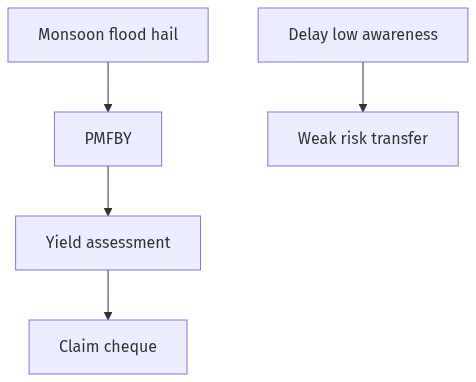
Conclusion
Crop insurance, led by PMFBY, is U.P.’s main formal farm-risk tool. It transfers yield shock when enrolment, subsidy, and assessment work. Impact falls where claims lag or plots sit outside the notified average. Risk management still needs irrigation and soil health beside the policy.
Quick related
Students also ask
-
As per Taj Trapezium Zone Pollution (Prevention and Control) Authority, what are the criteria for the four types of categorization of industries, namely Red, Green, Orange and White?
Next question in the 2025 paper (Q17). View answer →
-
Does PMFBY cover every fruit orchard automatically?
No. Only notified crops and seasons in notified areas. Many horticulture risks need a separate or additional product.
-
Is insurance a substitute for irrigation?
No. Insurance pays after loss. Irrigation and drainage reduce the loss. Both are risk management.
Same topic · past papers
UPPSC has asked this before
These previous-year questions sit on the same topic. Open one to practise the earlier ask.
-
2025 · Q2 · UPGS6 · 8 marks
What is the concept of Invest U.P.? Evaluate its role in the economic development of Uttar Pradesh. -
2025 · Q5 · UPGS6 · 8 marks
Briefly evaluate the major schemes launched by Government of Uttar Pradesh to promote silk production. -
2025 · Q14 · UPGS6 · 12 marks
In the Bundelkhand region of Uttar Pradesh, the mining industry is in a state of illness not due to a lack of minerals, but due to poor management. Evaluate the above statement. -
2024 · Q11 · UPGS6 · 12 marks
Critically evaluate the achievements of global investor summits organized by the Uttar Pradesh Government.
More from this paper
Q1 · UPSC Mains 2025 · UPGS6 · 8 marks · Solution
Discuss the recent tax reforms undertaken by the Uttar Pradesh Government.
Public finance and ODOP
U.P. tax reform after GST is mainly stamp duty, electricity duty, SGST incentives, and online commercial tax. Industrial policy uses those three state tools to attract plants. Digitised registration and e-way bills cut compliance delay. Households see stamp-duty concessions more clearly than GST rates, which are Union-led. The state cannot rewrite GST slabs; it can only run administration and property-linked taxes better.
Q2 · UPSC Mains 2025 · UPGS6 · 8 marks · Solution
What is the concept of Invest U.P.? Evaluate its role in the economic development of Uttar Pradesh.
Schemes, skill and investment
Invest U.P. is the state investment promotion agency, not a factory owner. It markets sectors and walks files through Nivesh Mitra. Summits and land banks are the pitch; after-care is the development test. It helps a land-locked state compete on speed of clearance. It cannot substitute power, logistics, or skills.
Q3 · UPSC Mains 2025 · UPGS6 · 8 marks · Solution
What is "Green Star Rating System" launched in 2025?
Economy, budget and industry of UP
U.P. launched a Green Star Rating in 2025 as a state mark for greener buildings and industry. Stars rest on energy, water, and waste performance. The rating is a signal for buyers and departments, not a replacement for pollution law. It has no privately invented ISO number in this answer. Its worth depends on audit, not on the logo alone.